

Borrow Money: Fast Cash Loan
4.7

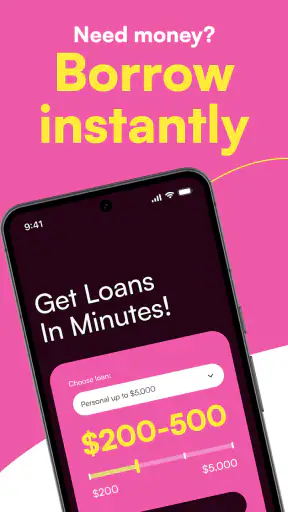
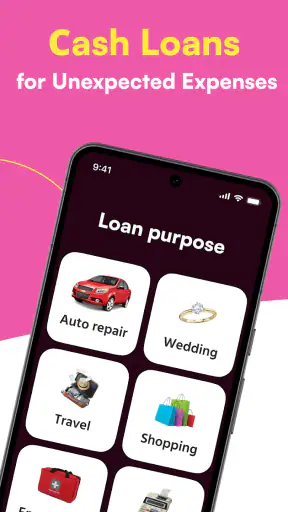
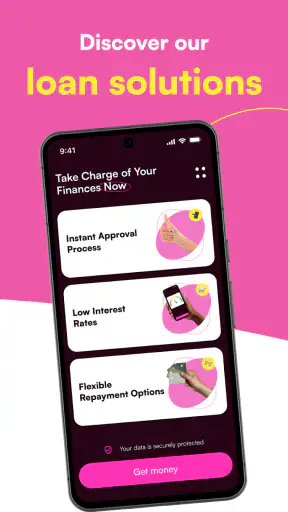
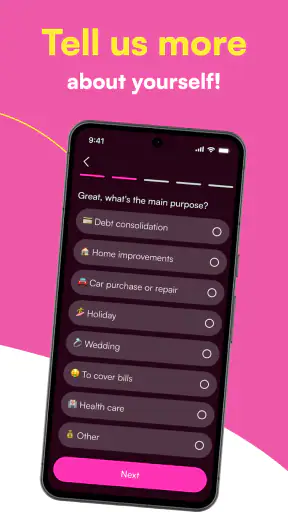
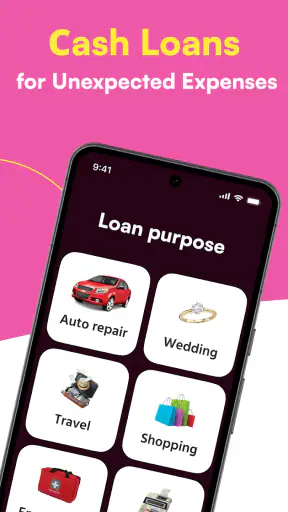
When an unexpected bill lands between paydays, the hardest part is often not deciding whether you need help, but understanding what you are agreeing to before you request it. Borrow Money: Fast Cash Loan is a finance app from Dollar Loan Center built around that short-term borrowing moment. I see it as a tool for people who want to begin a cash-advance or loan request from a phone rather than start with a branch visit or a long search through unrelated financial products.
The app is free to install, has an Everyone age rating, and is available for devices running Android 7.0 or later. It was released on August 6, 2024, and its current version is 0.2.2. Those details make it approachable for many Android users, but they do not turn borrowing into a risk-free decision. My main advice is simple: use the app to understand your options and handle a specific, necessary gap, not as a routine way to stretch every paycheck.
What to expect before you request money
The first thing I would keep in mind is that this is not a budgeting app, savings account, or general-purpose banking replacement. Its purpose is much narrower: helping users explore borrowing money through a mobile experience. The store positioning focuses on cash advances and fast loans, including people who may have bad credit. That makes it relevant when conventional credit feels difficult, but it also means I would approach every screen with extra attention.
A loan app can make the beginning of the process feel quick while leaving the most important decision until later: whether repayment will fit comfortably into your real budget. Before installing, I would identify the exact expense, the amount needed, and the date on which repayment could realistically happen. Writing those three points down prevents a vague request from becoming a larger commitment than intended.
The app has attracted an average rating of 4.7 from around 21 thousand ratings, with roughly 1.1 thousand written reviews and over 100 thousand installs. That level of adoption suggests that many people find the mobile approach useful, but popularity is not a substitute for reading the terms attached to an individual offer. A positive store score can tell me that the experience is generally well received; it cannot decide whether a particular loan is affordable for me.
The most important success measure is not how quickly I reach an application screen, but whether I understand the total repayment before accepting anything. I would look for the amount received, the amount to be repaid, the due dates, and any fees or other costs shown during the process. If those details are unclear, I would pause rather than rely on an assumption based on the requested amount.
This distinction matters especially for someone with damaged or limited credit. A service that considers borrowers conventional lenders might overlook can be useful in a genuine emergency, but access to money does not automatically mean the offer is inexpensive. I would compare the full cost with alternatives such as asking a utility provider for a payment arrangement, speaking with an employer about an advance, using an existing emergency fund, or checking a credit union option.
Who is likely to benefit
I think the app is best suited to an adult who has a defined short-term need, knows the next income date, and can review financial details without feeling pressured by urgency. It may also suit someone who prefers completing an initial borrowing request on a phone and wants a more direct starting point than visiting multiple lenders individually.
It is a weaker fit for anyone already juggling several loans, regularly using one payday advance to repay another, or unsure how the next repayment would fit alongside rent, food, transportation, and existing bills. In that situation, a new application may postpone the problem while increasing the total pressure. A nonprofit debt counselor or a conversation with creditors may be more appropriate than another short-term borrowing cycle.
The app is also not the right choice for someone expecting a guaranteed approval or immediate money simply because the description emphasizes speed. A request still involves an evaluation, and the result can depend on information supplied during the process. I would treat the app as a way to apply or explore an option, not as a promise that funds will arrive on a particular schedule.
Getting from installation to a useful first result
Start with a prepared application
After installing, I would avoid opening the app while distracted or in the middle of a stressful payment deadline. The better workflow is to have basic personal and financial information available, use a private connection, and reserve enough time to read each prompt. Rushing increases the chance of entering an incorrect detail or accepting a condition without noticing it.
I would also check that the app is the one published by Dollar Loan Center before entering sensitive information. The developer name is an important identity check when searching an app store, particularly in a category where imitation applications can be a serious concern. I would install through the official Android store listing and keep the application updated rather than relying on an old copy.
The app is free to download, but “free” here describes installation, not the cost of borrowing. That is an easy distinction to miss when someone is worried about an immediate expense. I would never interpret the absence of an upfront download price as evidence that a loan itself has no fees, interest, or repayment cost. Those are separate questions that belong to the offer details.
During setup, I would enter information exactly as it appears on relevant documents and review numbers before moving forward. A small mistake in income, contact information, or employment details can create delays or require corrections. I would avoid guessing simply to get through a form faster. Accuracy is more useful than speed at this stage.
Make the first meaningful action a review, not an acceptance
For a first-time user, the most useful initial action is to proceed far enough to see what information and options the app presents, then stop and inspect the offer carefully. This creates a clear checkpoint. I can learn whether the requested amount and repayment structure make sense without treating the first available option as something I must accept.
I would compare the amount I need with the amount I can repay. If I need a smaller sum to cover a specific medication, repair, or bill, requesting more than necessary can increase the eventual burden. The practical tip is to separate the emergency expense from the emotional relief of seeing a larger amount available. Borrowing capacity is not the same as affordable borrowing.
Once an offer is displayed, I would read the repayment schedule from beginning to end. I would check whether the timing matches my income cycle and whether the payment would collide with fixed obligations. A repayment that looks manageable in isolation can become difficult when it arrives just before rent or insurance. I would put the due date in my calendar only after confirming that I understand it.
Another useful habit is to save the important details for my own records, provided the app and device allow that without exposing sensitive information. I would note the amount requested, the amount received, the total repayment, and the scheduled dates in a secure place. This helps me compare the offer with alternatives and makes it easier to track what I owe later.
A realistic emergency scenario
Imagine that my car needs a repair that affects my ability to get to work, and my next paycheck is several days away. I would first ask the repair shop whether a partial payment or short extension is possible. If that fails, I would check whether an employer advance, family arrangement, or existing credit line costs less. Only then would I open Borrow Money: Fast Cash Loan, request no more than the repair requires, and examine the full repayment before deciding.
If the repayment would leave me short on groceries or housing costs, I would not call the application a success merely because it produced an offer. The successful action would be finding a workable solution without replacing one emergency with another. This is where the app’s convenience needs to be balanced by personal discipline.
Where first-time users may hesitate
One common source of confusion is the difference between submitting a request and receiving money. A mobile application can streamline the request, but those stages are not identical. I would read the status language carefully and avoid making a payment commitment based on the assumption that funds are already available.
Another point that deserves attention is the phrase “bad credit.” I read it as an indication that the product is aimed at people who may have difficulty with traditional lenders, not as a guarantee that every applicant will qualify. It also should not be read as a reason to skip affordability checks. If credit history is weak, the cost and consequences of a new obligation deserve even more scrutiny.
I would also distinguish between the requested amount and the net amount that reaches me. Any deductions or costs shown in the agreement can affect how much money is actually available for the bill. If I need a precise amount, I would confirm the amount received rather than calculate it from the headline request alone.
If the app asks me to provide information I do not understand, I would stop and seek clarification through the official support route associated with the application or developer. I would not send identity documents, account details, or authentication codes to a person who contacts me unexpectedly outside the normal app process. This is a practical safety rule for any financial service, and it matters even more when money is urgently needed.
How it compares with familiar alternatives
Compared with visiting a traditional lender, the app’s main advantage is convenience. I can begin from an Android phone and organize the request without planning a branch visit. That is valuable for someone with limited transportation, an irregular schedule, or a need to review options privately.
Compared with a credit card, however, the app may be less flexible for repeated expenses. A card can provide an ongoing line of credit, while a short-term loan is tied to a specific repayment arrangement. The better option depends on the actual cost and whether I can pay down the balance reliably. I would compare total costs rather than choose based only on the speed of access.
Compared with borrowing from family or an employer, a formal app-based loan may feel more private and structured, but it can also create a financial obligation with terms I need to follow precisely. An employer advance or payment arrangement may be cheaper in some situations, while a personal agreement can create relationship strain in others. The important trade-off is not simply digital versus personal; it is cost, timing, privacy, and repayment risk.
Compared with a budgeting or savings app, this product addresses an immediate funding gap rather than helping prevent the next one. If I find myself opening it repeatedly, that pattern is useful information: the underlying problem may require a spending plan, bill negotiation, additional income, or debt support. In that case, the app may solve today’s shortage while leaving tomorrow’s shortage untouched.
Using the app responsibly after the first request
Once I have accepted a loan, I would treat repayment tracking as part of using the product, not as an afterthought. I would keep the due dates visible, preserve the agreement details, and check my account before each scheduled payment. If the app provides status information, I would use it to confirm progress rather than assume that a payment has been processed.
I would avoid taking a second advance to cover the first unless I had fully reviewed the consequences and had no safer alternative. Rolling short-term borrowing forward can make the original emergency much more expensive. A better next step may be contacting the lender early if a repayment problem appears, while also reviewing which bill can be delayed or renegotiated.
Because the application is relatively new, I would pay attention to updates and read release information when available. The current version is 0.2.2, so the experience may continue to change as the developer refines the product. Keeping it current can help with ordinary reliability, but an update should never be treated as a reason to overlook the financial agreement itself.
Privacy deserves the same care as repayment. I would use a screen lock, avoid leaving financial screens open in public, and remove stored information from the device if I no longer need it. I would also be cautious with screenshots because they can expose personal or account details to anyone who accesses my photo library.
My recommendation for a first-time borrower
My overall view is that Borrow Money: Fast Cash Loan offers a straightforward starting point for people who want to explore a short-term borrowing request from an Android phone. Its free installation, broad device compatibility, and strong user response make it easy to consider, while Dollar Loan Center gives the app a clearly identified developer behind the experience.
Still, I would recommend it selectively rather than universally. It makes the most sense when the expense is specific, the amount is limited, and the repayment plan is already realistic. It is not a good substitute for an emergency fund, long-term budgeting, or professional debt help, and I would skip it if the repayment would depend on another loan.
The best path from installation to a meaningful result is therefore deliberate: verify the developer, prepare accurate information, request only what the expense requires, inspect the complete repayment terms, compare alternatives, and accept only when the payment fits the rest of the month. Used that way, Borrow Money: Fast Cash Loan can be a practical option to investigate during a short financial gap without letting the app’s convenience make the decision for me.
For readers who want a quick mobile entry point into borrowing, I think it is worth examining. For readers seeking the cheapest long-term way to manage money, I would look first at savings, bill negotiations, credit-union products, or debt advice. The app can help with a moment; the right financial choice is the one that still looks manageable after that moment has passed.
4.7
1.06K Reviews
Pros
- Simple application process with minimal paperwork
- Fast eligibility checks can save time in urgent situations
- Loan details are presented in an easy-to-read format
- Useful repayment reminders help users track due dates
- Available on mobile for convenient access wherever you are
Cons
- Interest rates and fees may be high for some borrowers
- Approval and loan terms can vary by applicant
- Late payments may lead to additional charges
- Requires careful review of lender terms and privacy policies
- Not available or suitable for users in every region


